Category: Subscription ONLY
-
Cash Flow Investing: 2 big cap stocks with high dividend yield
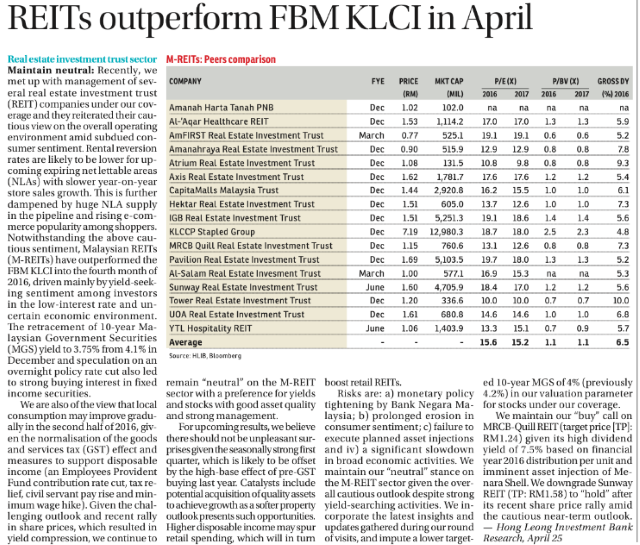
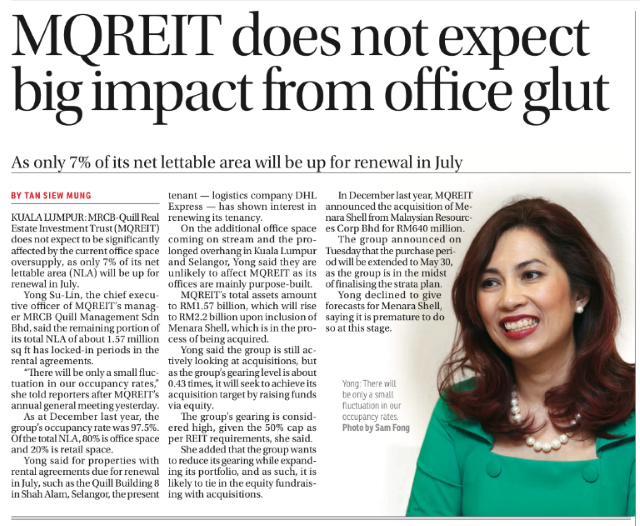
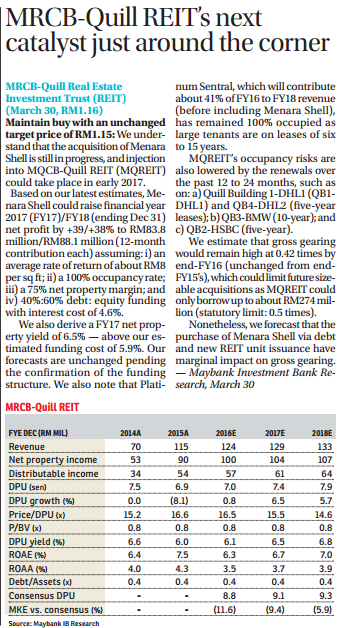
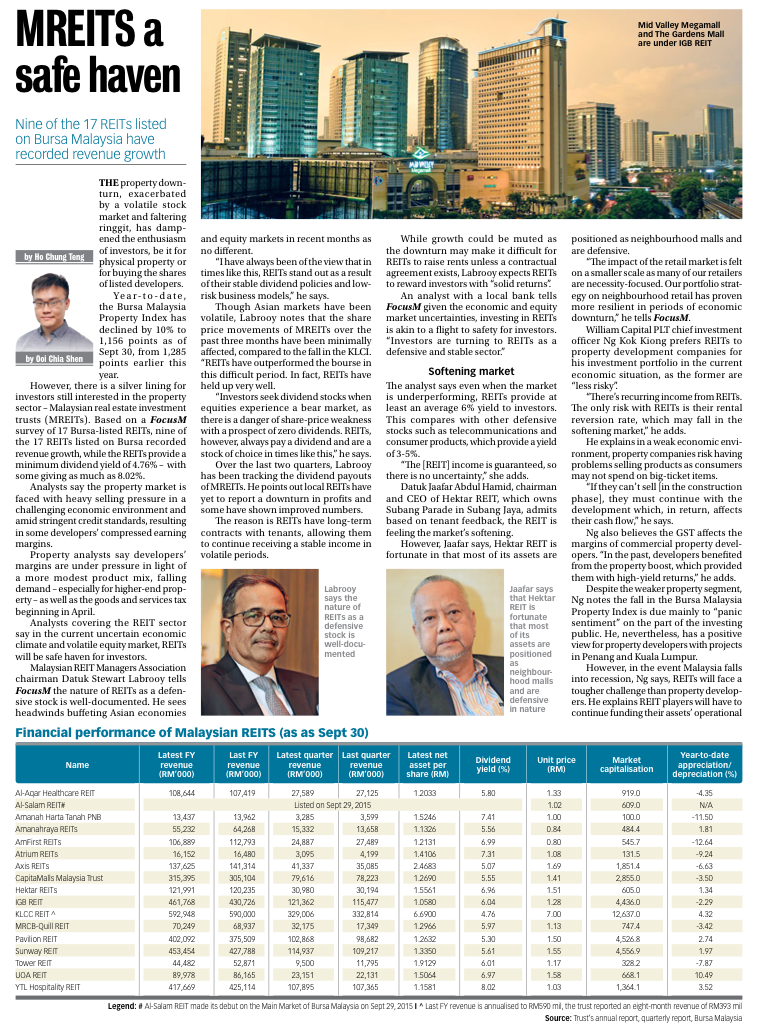
The reason for REIT investing is obviously for its sustainable and growing dividend yield. My criteria is 6 percent net yield or above, but for a REIT to have that kind of dividend yield in this market, the price has to drop quite a lot due to sentiment, and not due to deterioration of fundamentals, to make it a good buy. This very small windows of opportunity may only open say 2 out of the total trading days in a year, example MQREIT which I am holding at over 7% yield alone
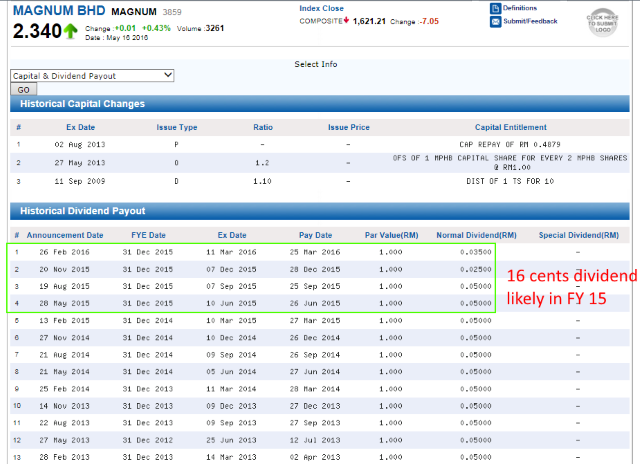
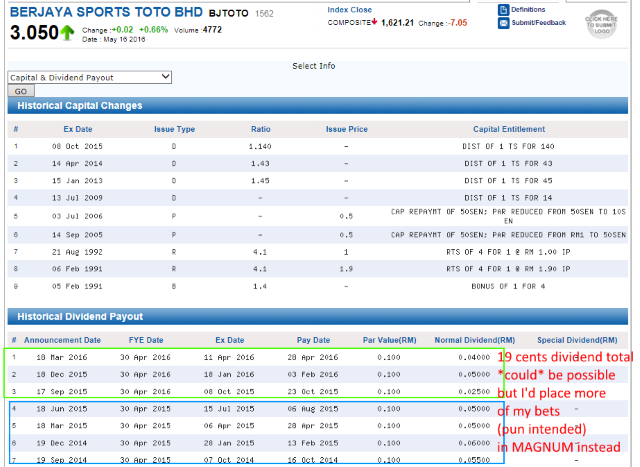
But this week, the price of 2 big cap dividend stocks with track record of sustainable+growing dividend payout has dropped, making its dividend yield at 6.9% and 6.3% respectively. Sustainable because it is in the consumer sector, and not a cyclical business, plus point is it exploits the fundamentals of human nature – greed for money. This is more attractive than any REIT counters can provide at the time of this writing. These 2 are competing sin stocks, namely MAGNUM and BJTOTO. I don’t bet numbers on MAGNUM or BJTOTO, but I will buy their stocks now.
Why the prices dropped:
- MAGNUM: marginal shrink of net profit from RM 256 mil to RM 226 mil, due to non-controllable factors: a) weakness in consumer spending & b) competition from illegal operators and controllable factor: fewer draw days.
- BJTOTO: massive shrink of net profit from RM 104 mil to RM 58 mil, with similar non-controllable factors as MAGNUM, on top of higher price payout.
Disclaimer: Opened substantial positions in these 2 counters 16 & 17 May 2016.
Analysis of Dividend Yield (even if the stock price stagnates)
MAGNUM – at 4 years resistance line
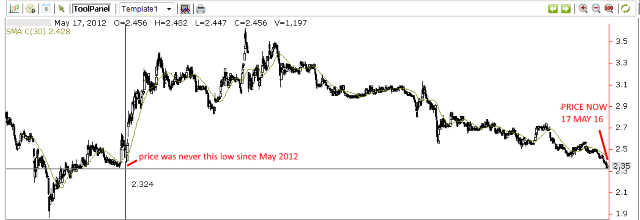
BJTOTO – at 10 years (!!!) resistance line.
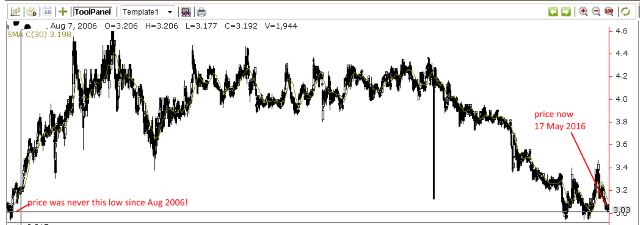
Disclaimer: This article contains the opinions of the author. The opinion of the author is subject to change without notice. All materials presented are compiled from sources believed to be reliable and current, but accuracy cannot be guaranteed. This article is distributed for educational purposes, and it is not to be construed as an offer, solicitation, recommendation, or invitation to buy/sell for the securities mentioned.
-
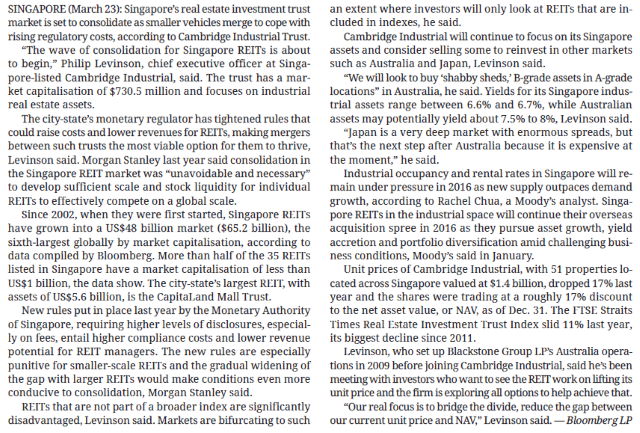
S-REIT to consolidate – but why?
This is like the Big Fish eating the Small Fish – but why?
Will it happen anytime soon in Malaysia? For example, Axis REIT buying out Atrium REIT?
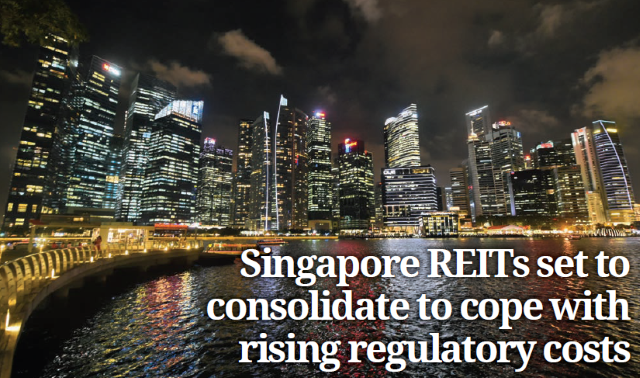
Read the below:
-
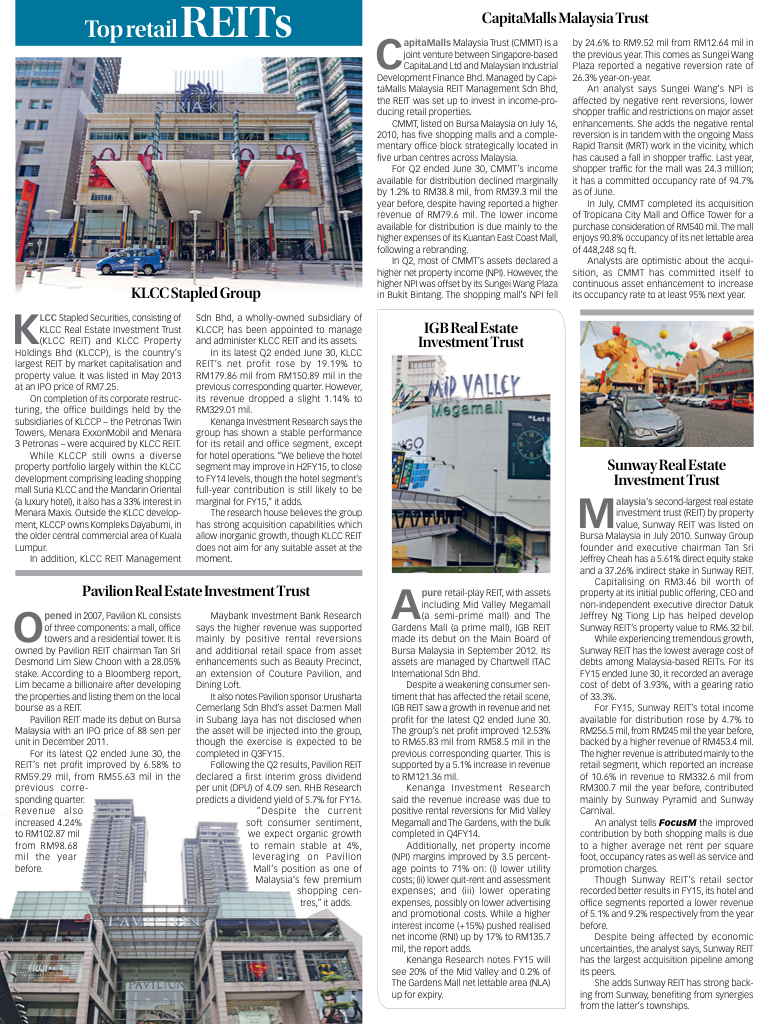
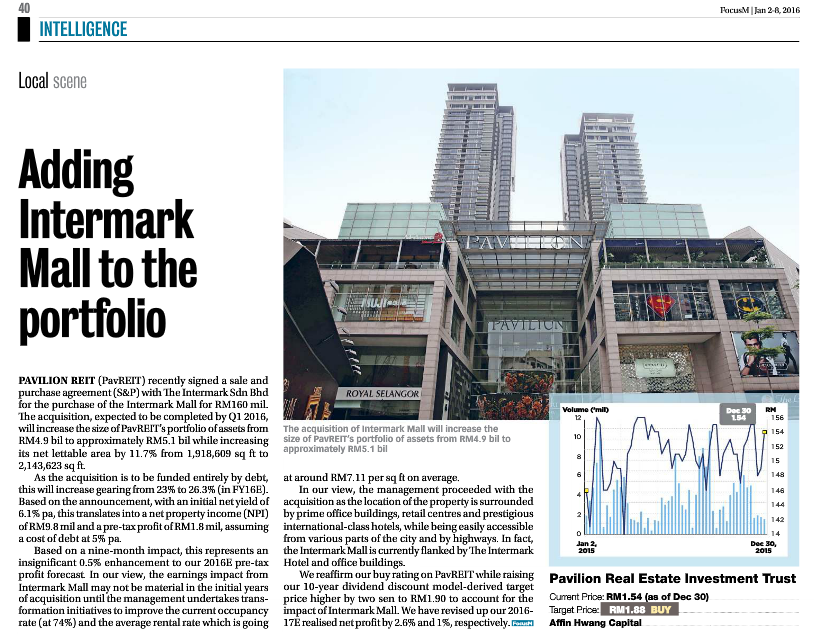
Pavilion REIT asset acquisition to kick start 2016
Anytime a REIT acquire new assets, it is newsworthy. Please be aware of the recent news below.
-
AmFirst REIT Property Disposal & Acquisition
This year, AmFirst REIT has been relatively active in new asset acquisition and disposal of assets to realize capital gain.
Read here: Disposal of Ambank Group Leadership Center – 15 Dec 2015
Read here: Acquisition of Mydin HyperMall Penang – 15 April 2015
What this means:
The disposal means additional income distribution due to the realized capital gain which is expected to be completed in the next 3 months from Dec 2015.
The disposal will have very minimal impact on the net property income because AGLC also accounts for 1. 26 mil of the total RM 76.5 mil in 2014.
However, the acquisition also means more steady future income distribution due to the fact its latest asset is a retail mall – moving away from being a pure play office REIT to a hybrid of office+retail REIT
We cannot predict what the annual DPU would be going forward, but the stock price as of the time of this writing is severely undervalued vs its NAV/unit. Which means, at the current entry price, your dividend yield could be easily at 6.5%+ assuming FYE of 2015. The risk is of course, the down trending of DPU starting 2 years ago.
Nonetheless, might be good to start accumulate, and if you are holding it already, do not dispose until you realize the upcoming divided due to AGLC disposal.
Disclosure: AmFIRST REIT in portfolio as of Dec 2015
-
How to : Subscribe to Rights Issues with Warrants
As of the time of this writing (Dec 2015), OCK, a counter in second board, has rights issues with warrants (maturity date at 15 Dec 2020 with RM 0.71 exercise price) attached to each shares as it moves from 2nd board to main board.
This is an example of how to subscribe to it as an existing holder of OCK.
Note: I have OCK as one of my relatively speculative mid term holdings compared to my REIT portfolio. It is not entirely speculative if you look at the business and prospects in an analyst report HERE (albeit a bit outdated).
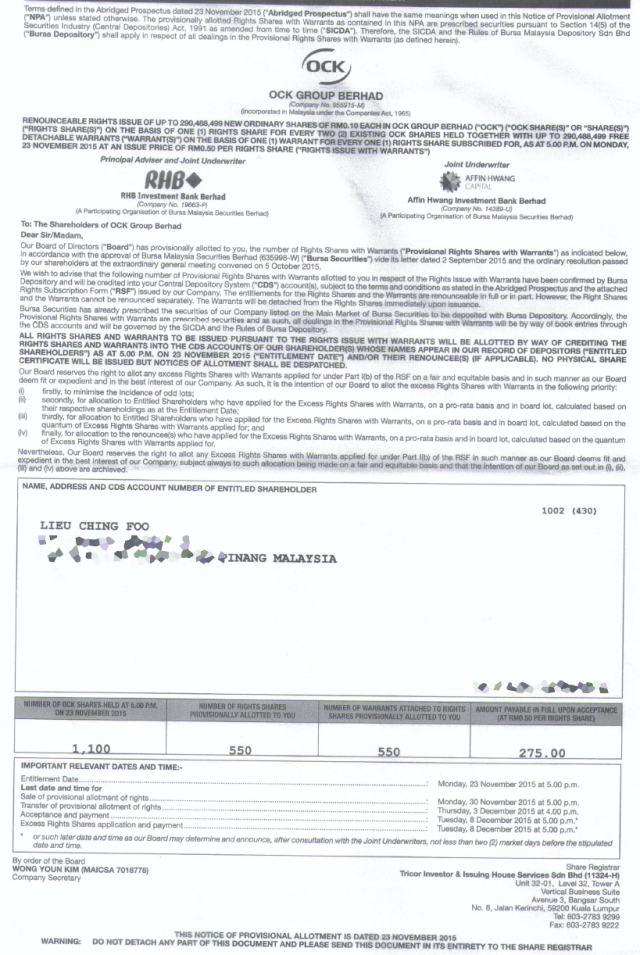
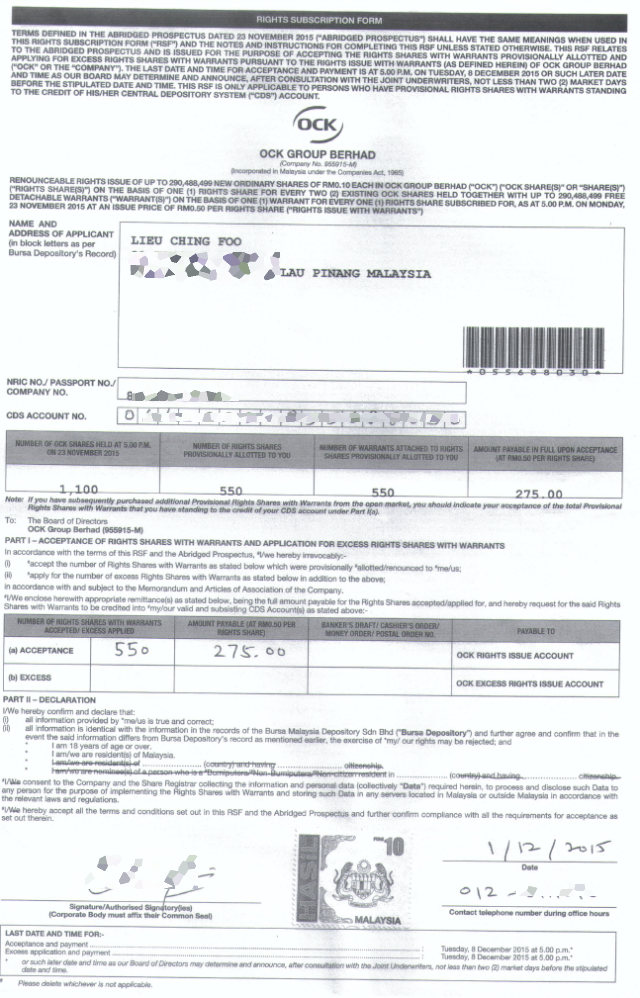
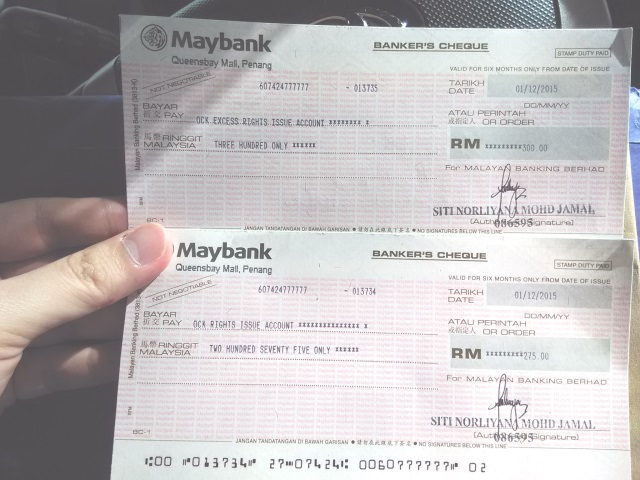
I subscribed additional 600 excess rights share for RM 300, which explains the below cheque, besides the RM 275 allocated to me.
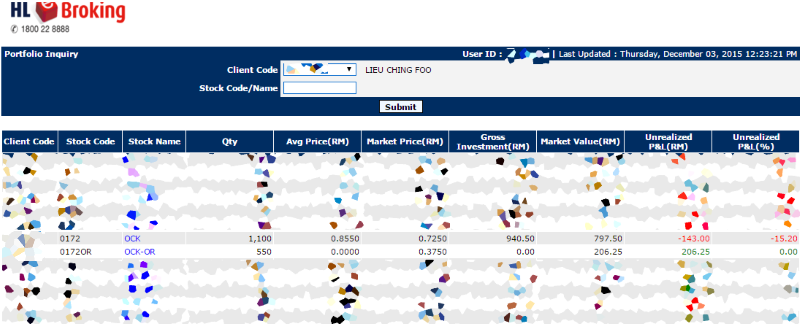
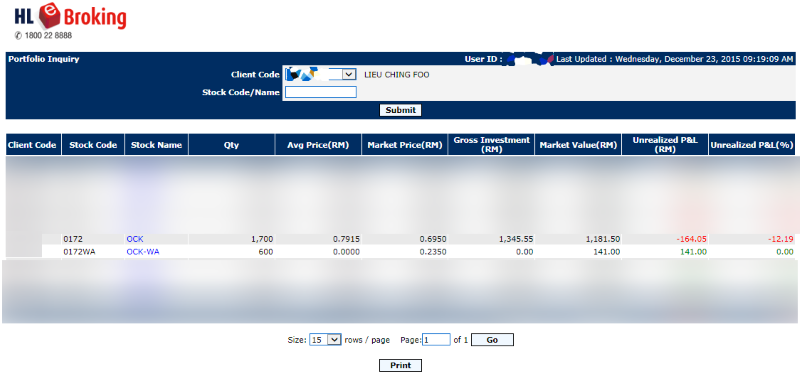
However, as you can see from my CDS account, I only got 50 of the 600 excess rights shares I applied; the amount I paid for the excess rights shares will be refunded to me.
-
AmFirstREIT Catalyst + Issues w/ ARREIT
See the attached PDF for AmFirst REIT acquiring Mydin Mall in Penang. This may potentially boost up his DPU going forward.
Another one is unofficial news on Amanah Raya REIT. Not so good one as it relates to 1MBD fiasco. One of the reason I never had ARREIT in my portfolio even though the yield is good.
http://www.freemalaysiatoday.com/category/nation/2015/06/10/amanah-raya-chiefs-kicked-out-over-1mdb/